CAPITAL SOLUTIONS · FOR FUND MANAGERS

    Raise it. Recapitalize it. Release the value in what it owns.

    Fund placement, GP-led and continuation solutions, a patient minority holder for assets the fund must return capital on, and co-investment programs alongside the main vehicle. For managers in energy, infrastructure and real assets, and selected private markets strategies.

    THE PROBLEM

    Capital formation has become a full-time job that competes with investing.

    Fundraising cycles are longer, allocators are more selective and more of them want co-investment, direct access or a clear liquidity story before they commit. At the same time, funds approaching end of life hold assets their LPs want returned and their GPs want to keep. The managers winning in this market are the ones who run capital formation as a disciplined process with the right partner, not as a side activity for the investment team.

    Saintrose runs that process: positioning and materials built to the standard institutional allocators apply, coverage of the LPs and capital providers that fit the strategy, and a senior team that has sat on the allocator's side of the table.
    SOLUTIONS

    Four solutions. One team.

    Fund placement

    Primary fundraising from first close to final, for emerging and established managers. Positioning and narrative, the full materials and data room, a targeted LP universe drawn from our database and our relationships, conviction-ordered outreach, and management of the process through diligence, capital calls and closing.

    GP-led and continuation solutions

    Continuation vehicles and GP-led secondaries that give existing LPs a liquidity option while the manager retains high-conviction assets. Structure, pricing guidance, buyer universe and process.

    Liquidity for fund-owned assets

    A patient minority holder for 20 to 35 percent of an operating energy or infrastructure asset that a fund must return capital on, or wants to hold past fund life. Saintrose structures and fills the position through a dedicated vehicle backed by institutional and family-office capital, so the fund realizes value without a full sale process and the GP keeps control of the asset.

    Co-investment programs

    Structuring and placing co-investment vehicles alongside the main fund, giving LPs the direct deal access they increasingly require while increasing the manager's capital under management.

    HOW IT WORKS

    The process allocators expect, run end to end.

    Assess

    Track record attribution, returns dispersion and deal-level contribution analysis; the strategy's edge against the vintages and strategies allocators will compare it with; the materials gap against institutional standard; the realistic LP universe for the size and strategy. Every question an allocator will raise is answered in writing before the first meeting.

    Position

    The investment thesis built around the strategy's structural edge; the materials suite allocators expect, from pitch deck and private placement memorandum to DDQ, data room and benchmarking pack; narrative architecture that stays consistent from first meeting through diligence.

    Match

    Profiles on more than 100,000 institutional investors, including pension funds, sovereign wealth funds, insurers, endowments and foundations, funds of funds, consultants and qualified family offices, maintained with mandate status and recent allocation activity. We identify the allocators whose ticket size, strategy appetite and current program fit your fund and approach them in conviction order with controlled, confidential introductions.

    Close

    Parallel management of allocators through diligence, operational due diligence support, data room and DDQ handling measured in hours, negotiation of side letters and terms with the manager's economics protected, and a structured process to first and final close. Relationships are handed over cleanly for the next fund.

    THE BENCH

    Advisors who have sat on the allocator's side.

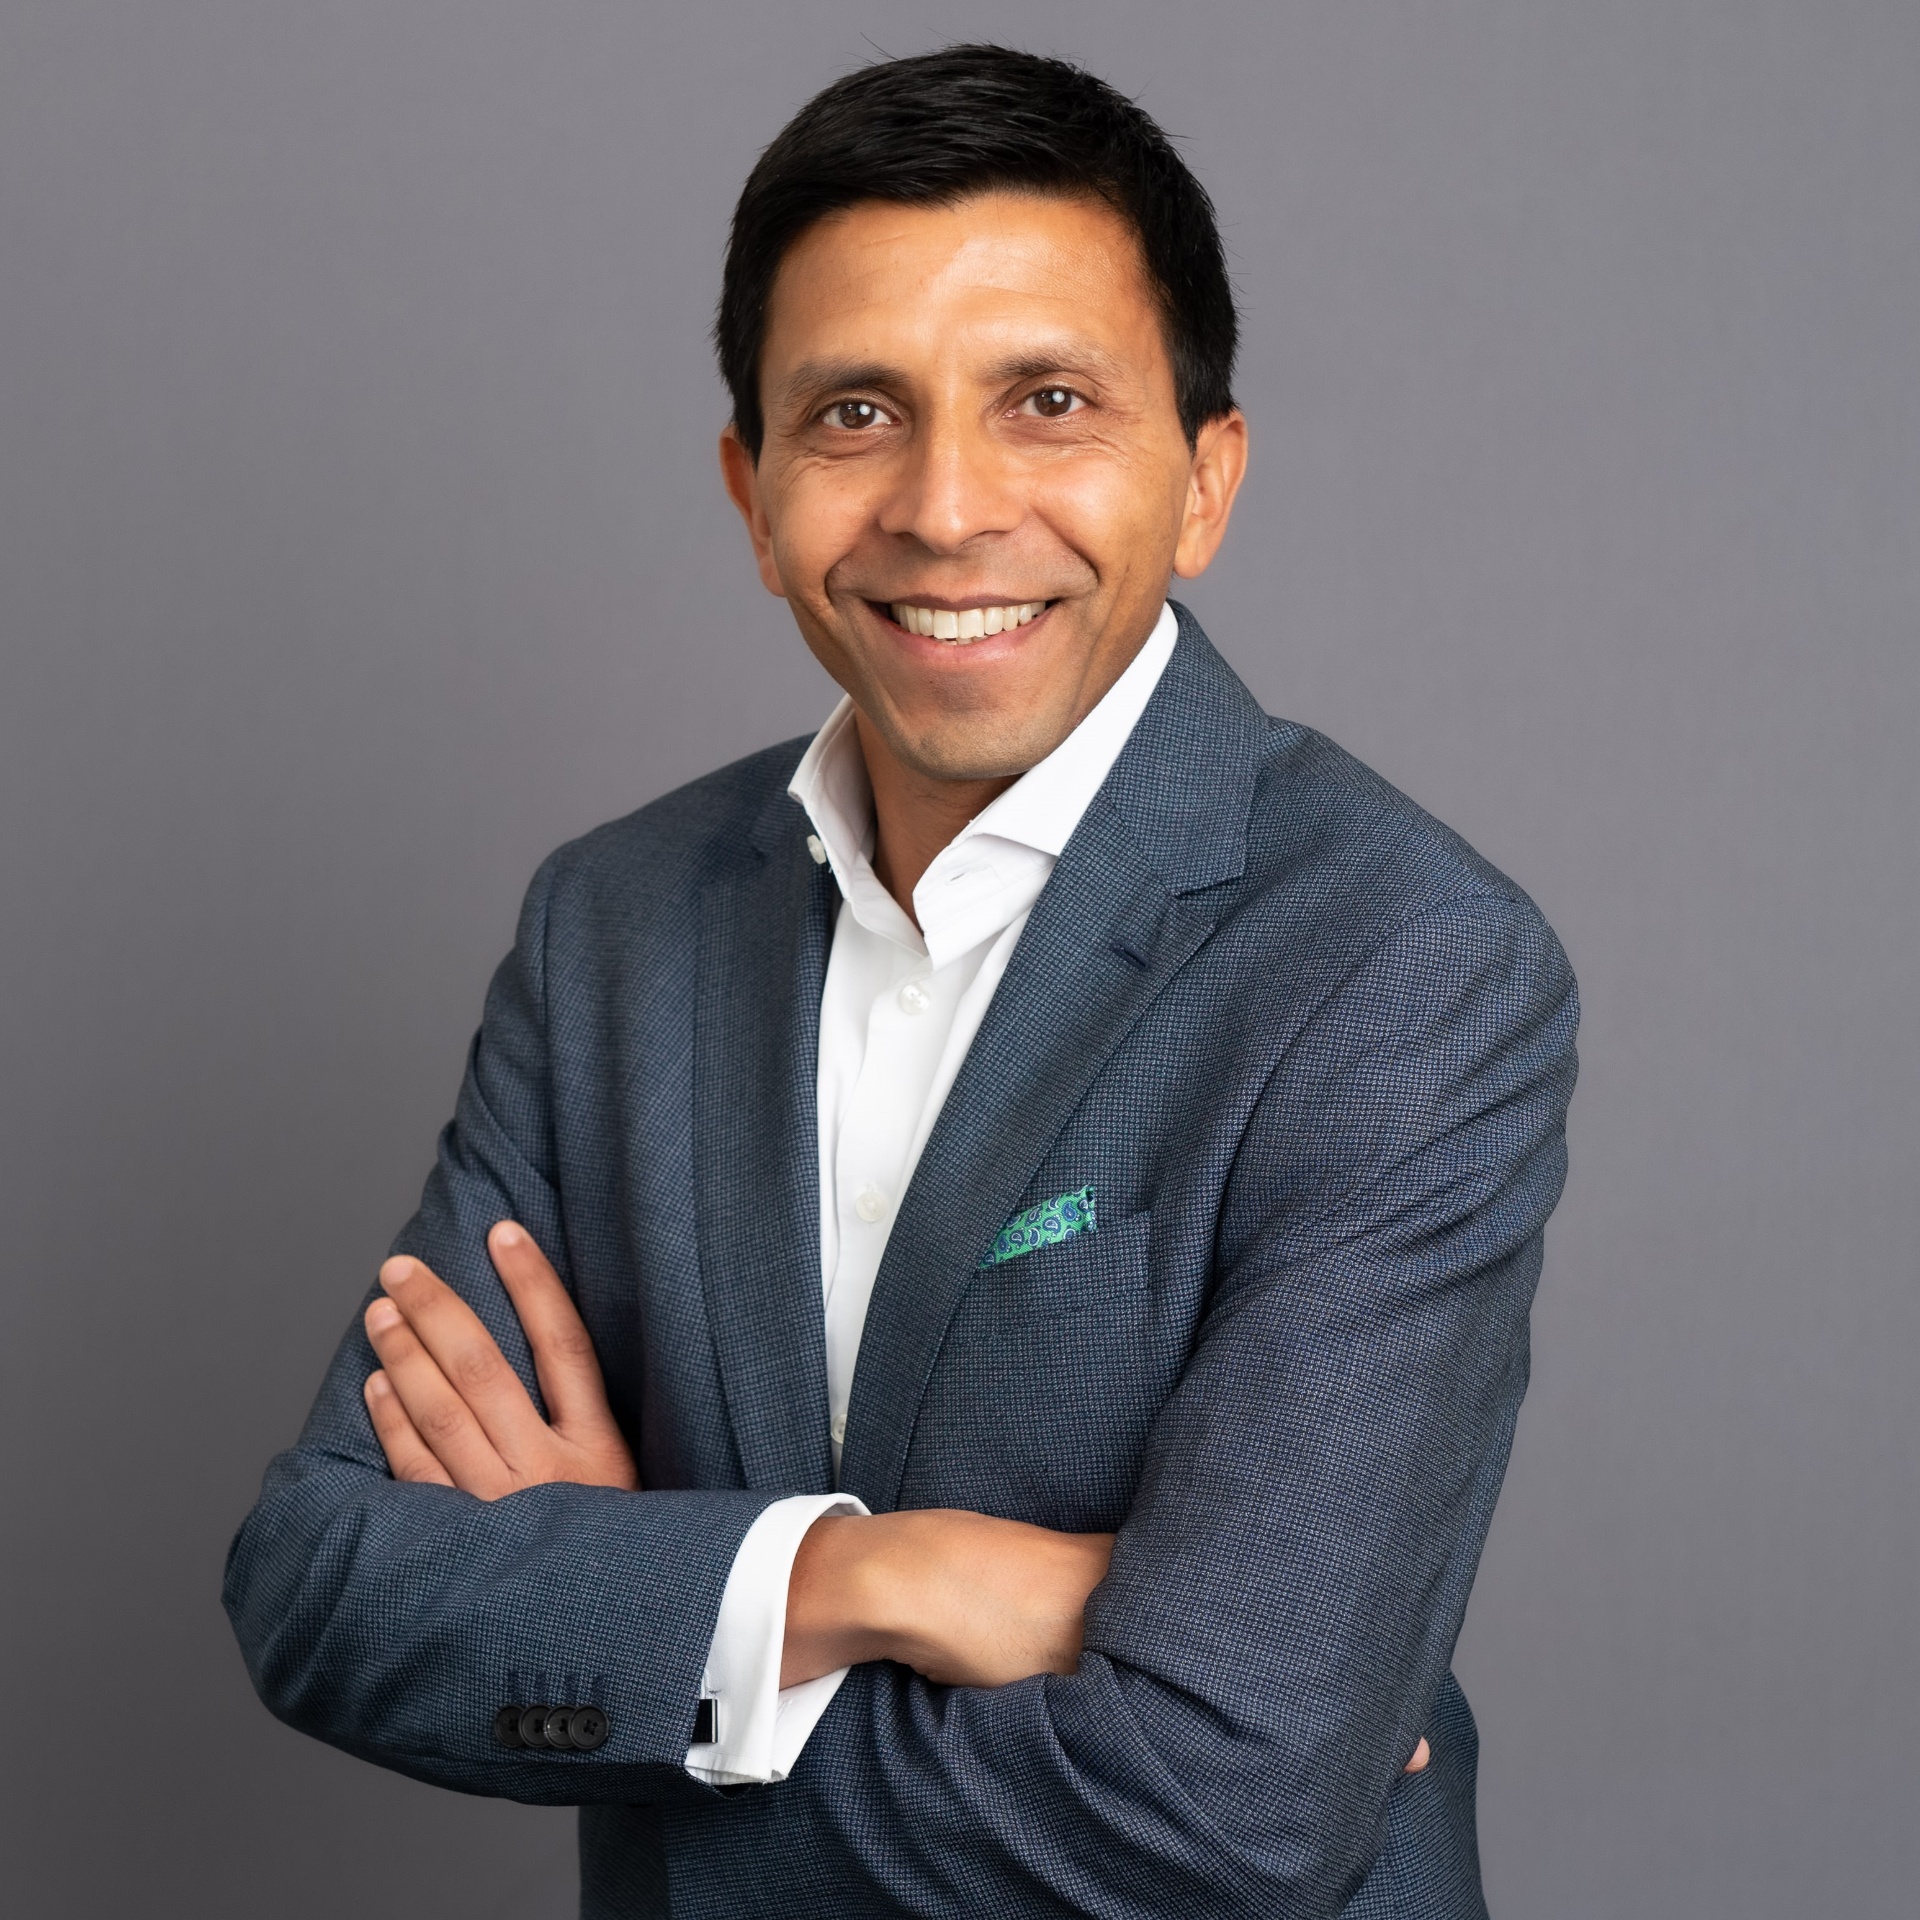
    Adam Wardi

    Adam Wardi

    Founder and Managing Partner

    Leads every fund mandate end to end and is the manager's senior point of contact on positioning, terms and the LP campaign. Finance professional and entrepreneur with institutional capital markets expertise; has raised over $100 million in the United States and deployed that capital in M&A transactions.

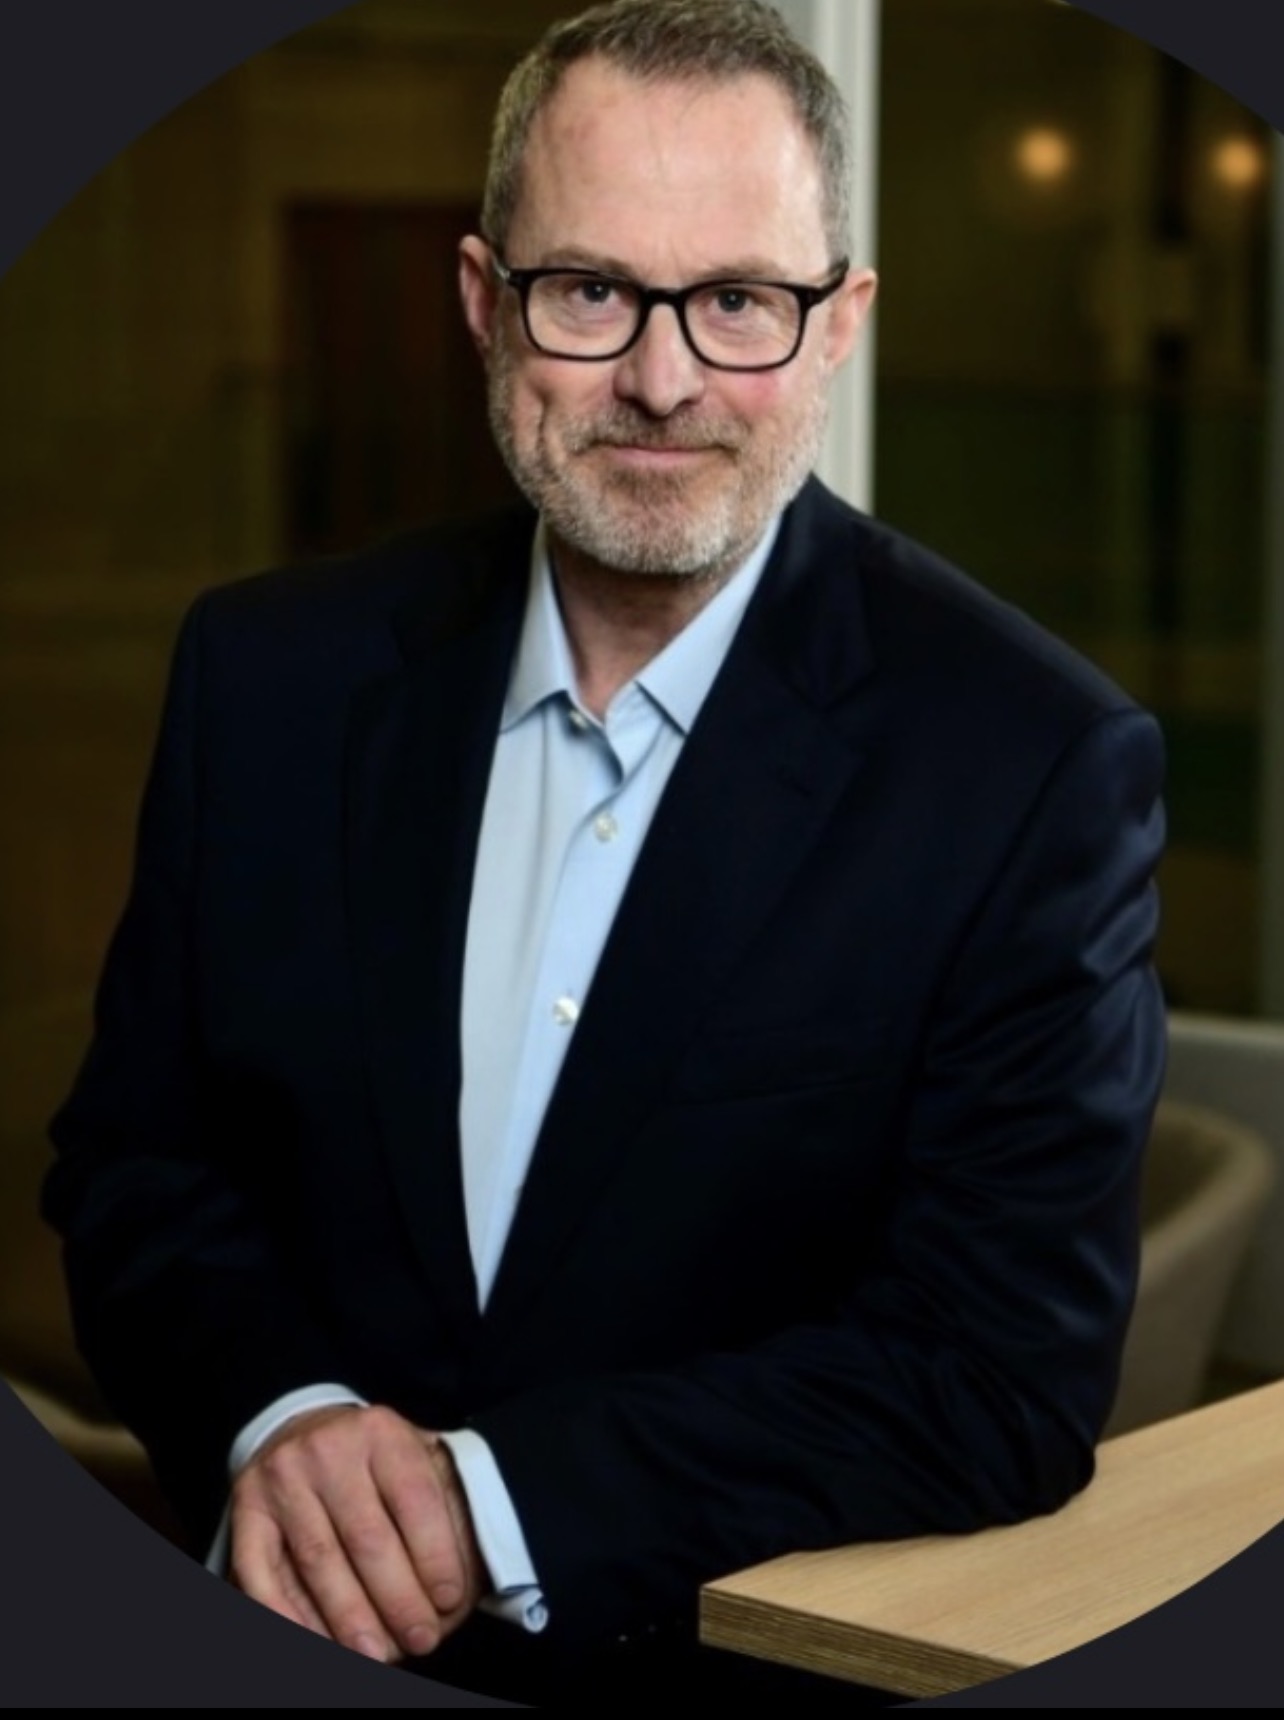
    Anil Mangla

    Anil Mangla

    Advisor

    More than twenty years in global financial services across BlackRock, Barclays Capital, Sera Global (a Brookfield portfolio company) and Copenhagen Infrastructure Partners. At BlackRock he was COO of a $400 billion institutional investor business, and over his career he has advised on and enabled multi-billion fundraising strategies in private markets. Extensive exposure to sovereign wealth funds, pension funds and global allocators: the precise LP profile required to inform and shape a Tier 1 capital formation strategy.

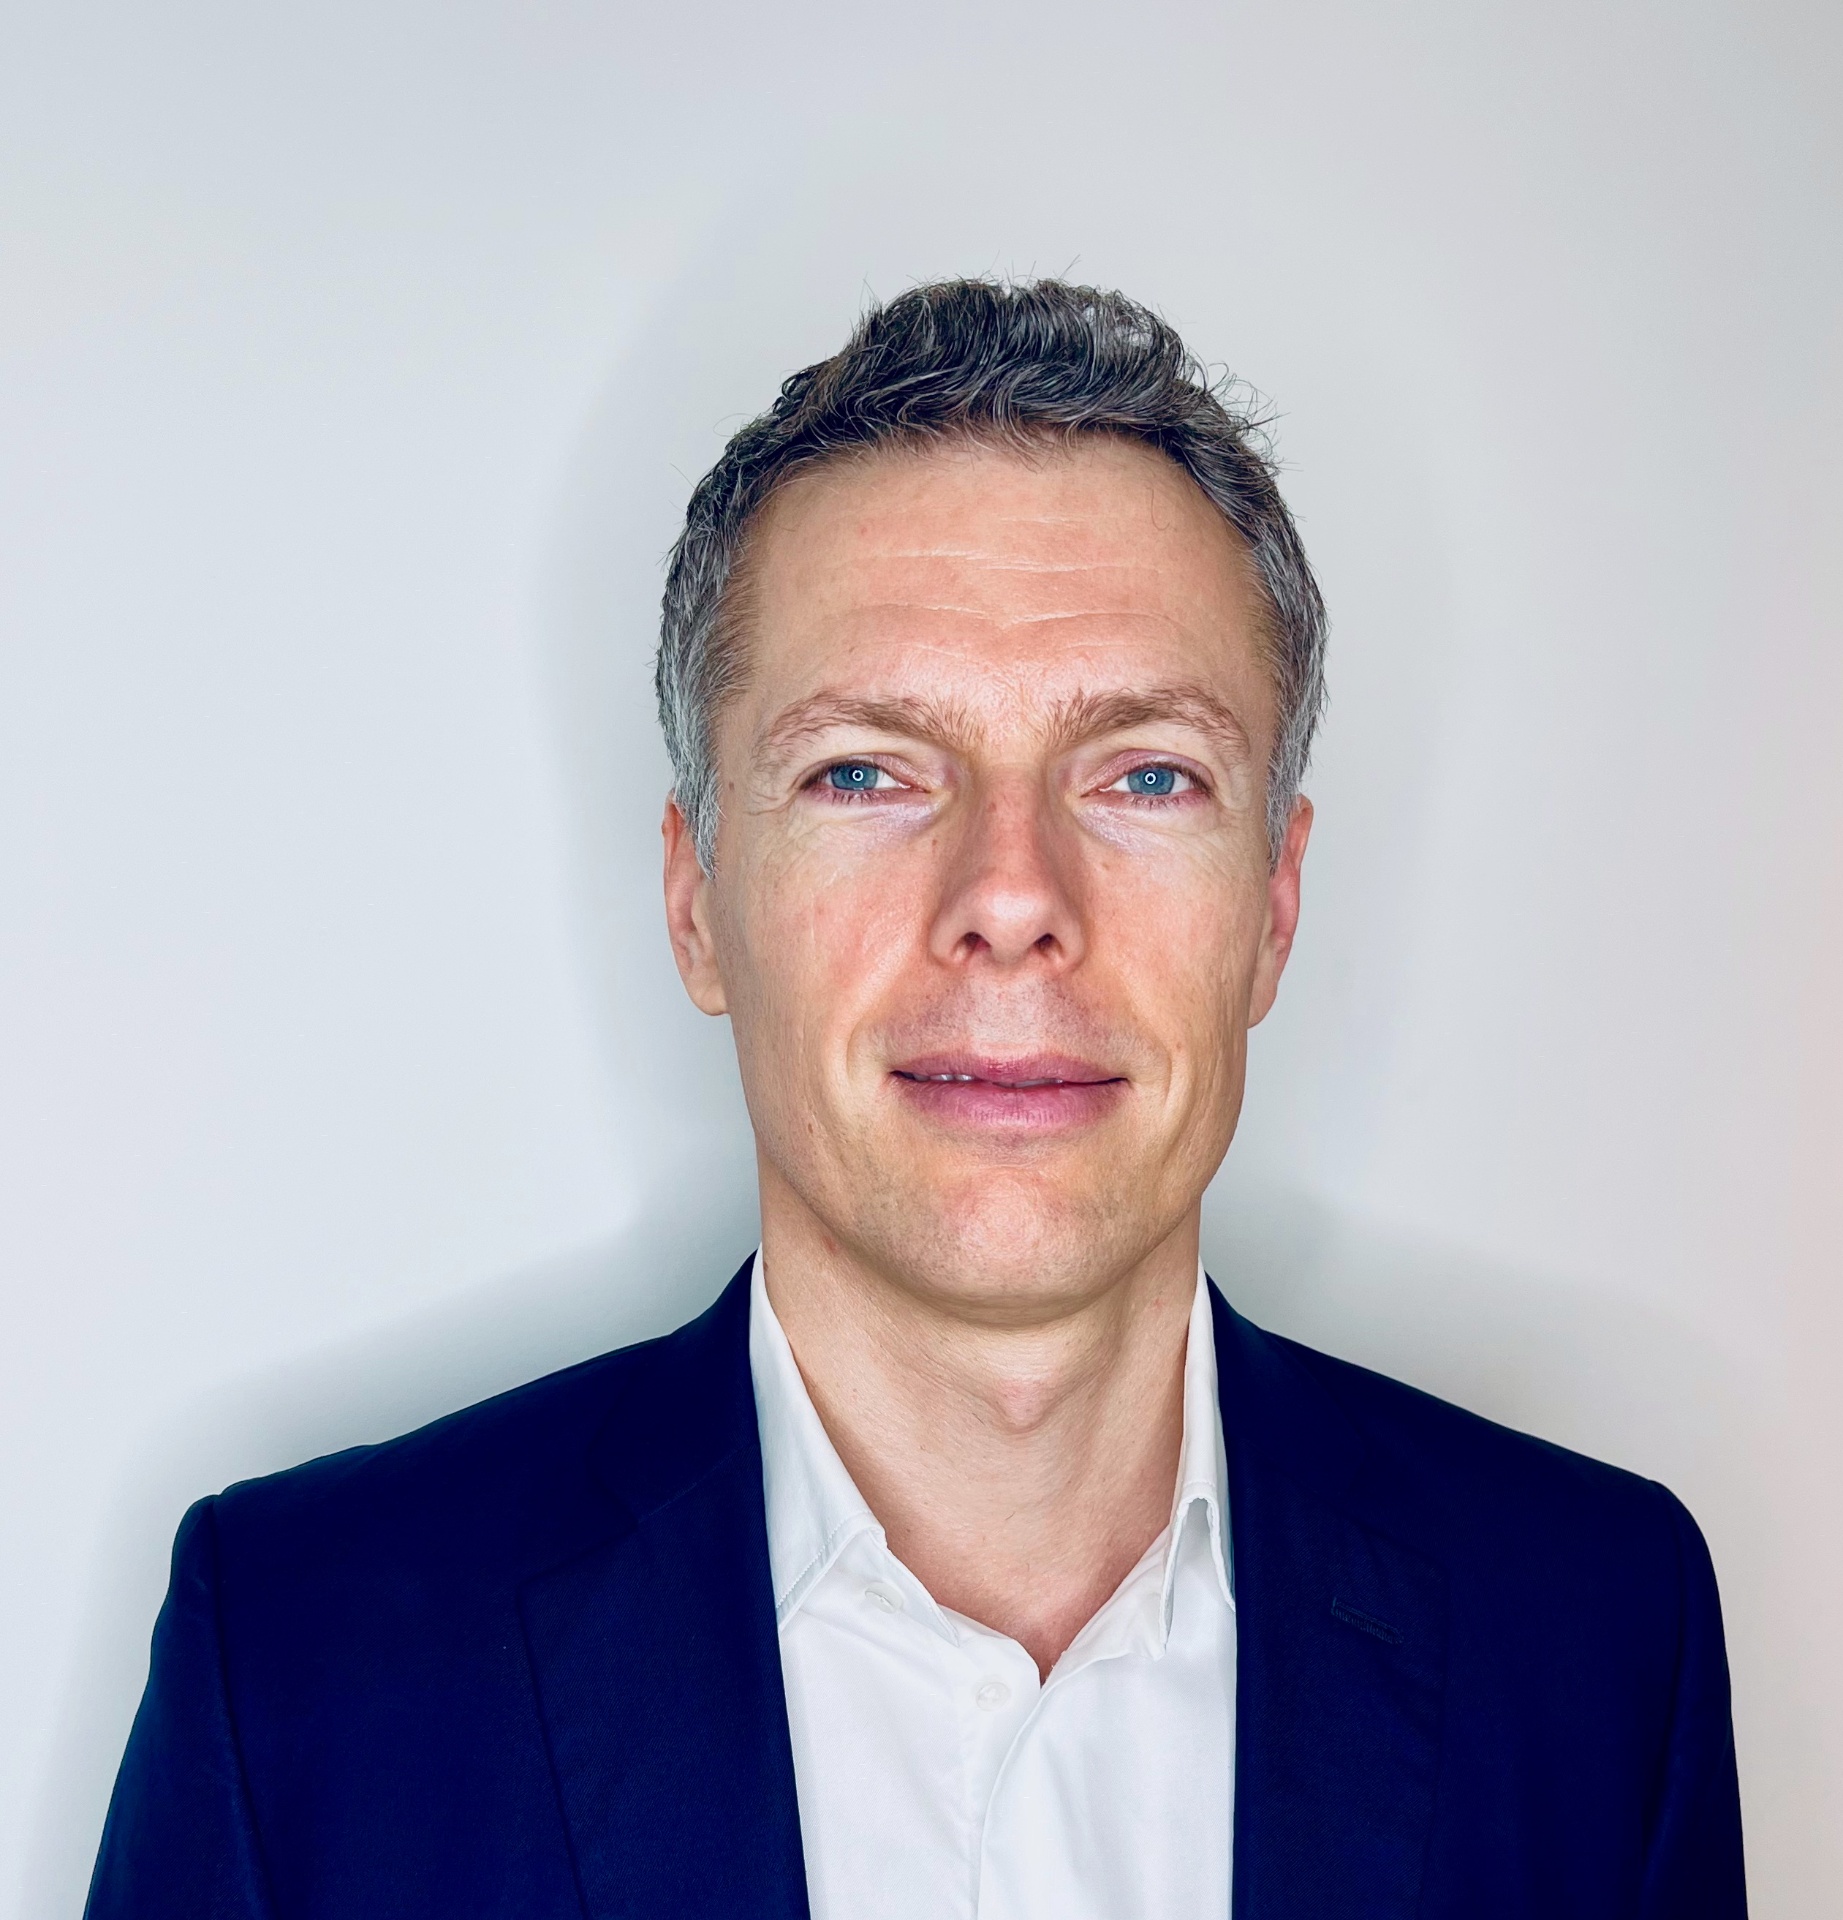
    Gary Ward

    Gary Ward

    Advisor

    Thirty years in private equity and corporate finance, including as Partner of a £1 billion mid-market private equity house. Gary has raised and deployed institutional capital himself and brings an extensive personal network of family offices, funds and high-net-worth investors, the relationship-led channel that anchor commitments and first closes depend on.

    Wayne Hiley

    Wayne Hiley

    Advisor

    Twenty years in corporate debt markets; led Debt Structuring at Barclays UK Corporate Bank and raised over £200 billion as Head of Corporate Bond Syndicate. Wayne advises on credit strategies and on fund-level and asset-level financing where a mandate requires it.

    The partners are supported by a deal team of associates and analysts across Zurich, Dubai and London who build the materials, the data room and the LP universe for every mandate.

    OUR ECONOMICS

    Aligned with the close.

    Fund placement and GP-led mandates are placement engagements through our broker-dealer arrangement: an upfront engagement fee scaled to the mandate, which funds positioning, materials and the first wave of institutional outreach, followed by success fees on capital actually raised from investors we introduce, set out in the engagement letter. Minority-stake liquidity transactions are structured through a dedicated vehicle and priced at the asset level, with economics agreed per transaction. In every case the substantive economics are earned when capital closes.

    FIT

    Managers we can place.

    It is for you if:

    • You have a differentiated strategy, institutional-quality operations and a track record or pedigree allocators can underwrite.
    • Your strategy sits in energy, infrastructure or real assets, or in a private markets strategy where our coverage is deep.
    • You have a defined capital need and a realistic timeline, whether that is a first close, a final close, a continuation vehicle or liquidity for a specific asset.
    • You want a process run by a senior team, not a list of introductions.

    It is not for: managers with no track record and no pedigree · retail or non-institutional products · strategies outside our coverage · raises that already have an exclusive placement agent.

    QUESTIONS

    We are a first-time fund. Can you place us?

    Where the team has a pedigree allocators can underwrite and the strategy is in our coverage, yes. First-time funds are a positioning and anchor-LP problem before they are an outreach problem, and that is where the work starts.

    How is minority-stake liquidity different from a secondary sale?

    A secondary sells the fund's interest or the whole asset. Minority-stake liquidity sells 20 to 35 percent of a single operating asset to a patient holder we bring, so the fund returns capital on that asset while the GP keeps control and the upside on the rest.

    Which LPs do you actually reach?

    Pensions, sovereign wealth funds, insurers, endowments and foundations, funds of funds, consultants and qualified family offices across every major geography. For each mandate we build the universe from our database and our relationships and show it to you before outreach begins.

    How long does a raise take?

    It depends on the manager's history, the strategy and the market. We map milestones at kickoff and report weekly against them.

    Tell us about the fund.

    A thirty-minute conversation with a partner. We will tell you how allocators are likely to read the strategy, which of the four solutions fits your situation, and whether Saintrose is the right firm to run it.