EXIT ADVISORY · FOR BUSINESS OWNERS

    Sell your company for the most it can be worth.

    Ready to sell now or two years out, we value your company the way a buyer will first, fix what suppresses its value only when there is time and it pays, then run a competitive process to the full buyer universe for the best offer on price and on terms.

    THE PROBLEM

    A buyer does not pay for last year's profit.

    A buyer pays for how confident they are that the profit continues after you leave, and for how easy the company is to own without you. If the sales depend on you, if one customer is a third of revenue, if the numbers arrive six weeks late, if every decision crosses your desk, a buyer will find it in the first two weeks of diligence. They will not treat it as an operating problem. They will treat it as leverage: a lower price, worse terms, a longer stay for you after the sale, a late renegotiation, or no deal at all.

    By the time most owners hire a broker or a bank, these issues are already baked into the company and there is no time left to fix them. The advisor's only job becomes negotiating around weaknesses that could have been removed.

    A problem found twelve months before the sale can usually be fixed. The same problem found six weeks after a letter of intent costs you money.

    WHAT WE DO DIFFERENTLY

    Value it like a buyer first. Prepare where it pays. Run a competitive sale.

    The traditional path

    1. Hire a broker the week you decide to sell

    2. Go to market as the company is, weaknesses included

    3. Buyers find every weakness in the first two weeks of diligence

    4. Each one becomes leverage: a lower multiple, a lower accepted EBITDA, an earnout, a holdback

    5. Take the structure you are offered, or walk away six months in

    The Saintrose path

    1. Value the company the way a buyer will

    2. Recommend going to market now or fixing a few specific things first

    3. Where preparation pays, close the Value Gap and prove the improvement

    4. Market the asset to the full buyer universe

    5. Bring several serious buyers to the table

    6. Leverage the multiple offers to maximise the valuation

    7. Close

    You are not buying a consulting program and hiring a bank later. You are hiring the bank now, whether the company is ready to sell or needs preparation. We charge the same transaction success fee whether we are engaged at launch or eighteen months before it. Preparation is undertaken only when there is time and the expected improvement justifies it.

    HOW IT WORKS

    Four steps. From the first assessment to closing.

    Value it like a buyer

    In the first weeks we look at your company the way a sophisticated buyer will: financial quality, commercial predictability, founder dependency, management and operations, and transaction readiness. You receive an estimate of what a buyer would pay today, what the company could support if the most important buyer concerns were addressed, and the Value Gap between the two. We rank the causes by what is worth fixing and end with a recommendation: go to market now, or fix a few specific things first.

    Close the Value Gap, where it pays

    Where preparation is worth the time, we agree a custom Exit Plan focused on the one or two priorities that matter most, with your management team implementing the changes and a dedicated Saintrose advisor guiding and reviewing the work. We prove the improvement with evidence a buyer can verify and revisit the number every 60 to 90 days, stopping when further preparation no longer pays; this step is skipped when the company is already ready.

    Market the asset

    We build the equity story, normalize EBITDA with defensible adjustments that survive a quality-of-earnings review, and prepare the data room before anyone asks. The teaser and confidential information memorandum are built to private equity investment committee standards. From more than 100,000 profiles we build the full buyer universe: strategic buyers, private equity platforms and their portfolio companies, family offices and independent sponsors. Outreach is confidential and ordered by conviction, not broadcast. We run management meetings and parallel buyer tracks, with the aim of having several serious buyers at the table at the same time.

    Our goal is to bring multiple serious buyers into competition, driving the valuation up while strengthening the terms.

    Close

    We compare every offer on what it is actually worth to you, negotiate the letter of intent with your price protected and every term scrutinized, and manage diligence through to signed documentation and closing. We coordinate legal, tax and accounting advisors, and commission sell-side quality-of-earnings work where warranted, so the financial case is tested before a buyer uses it to renegotiate.

    WHAT GETS FIXED

    Everything we do answers one of three questions.

    1 · "Will these earnings continue after I buy?"

    Predictable earnings. The commercial engine a buyer can forecast from: how you win customers, how you keep them, how you price, how much depends on a few accounts, and whether anyone other than you can forecast next year. Sales process and management, sales leadership without the founder, revenue durability and concentration, retention and expansion, pricing and margin.

    2 · "Will the company work when the owner leaves?"

    An institutionalized company. Who runs what, who decides what, whether there is a management rhythm, whether customers and suppliers know anyone but you, and whether the critical knowledge lives anywhere other than your head. Leadership structure, management scorecards and KPIs, a weekly and monthly cadence, delegation of decisions and relationships, documentation of the handful of processes that matter, and a founder independence test that produces the proof.

    3 · "Can I verify the numbers, and will other buyers compete?"

    A prepared, competitive exit. Mostly our work rather than yours: defensible numbers, a data room built before anyone asks, a story that holds under diligence, the right buyer universe and a process that creates tension. You receive a short guide so you understand what is happening. You are not asked to do it.

    THE BENCH

    People who have bought, sold and financed companies like yours.

    Your mandate is led by a partner and supported by advisors who have spent their careers on the buyer's side of the table, which is the side that sets the price.

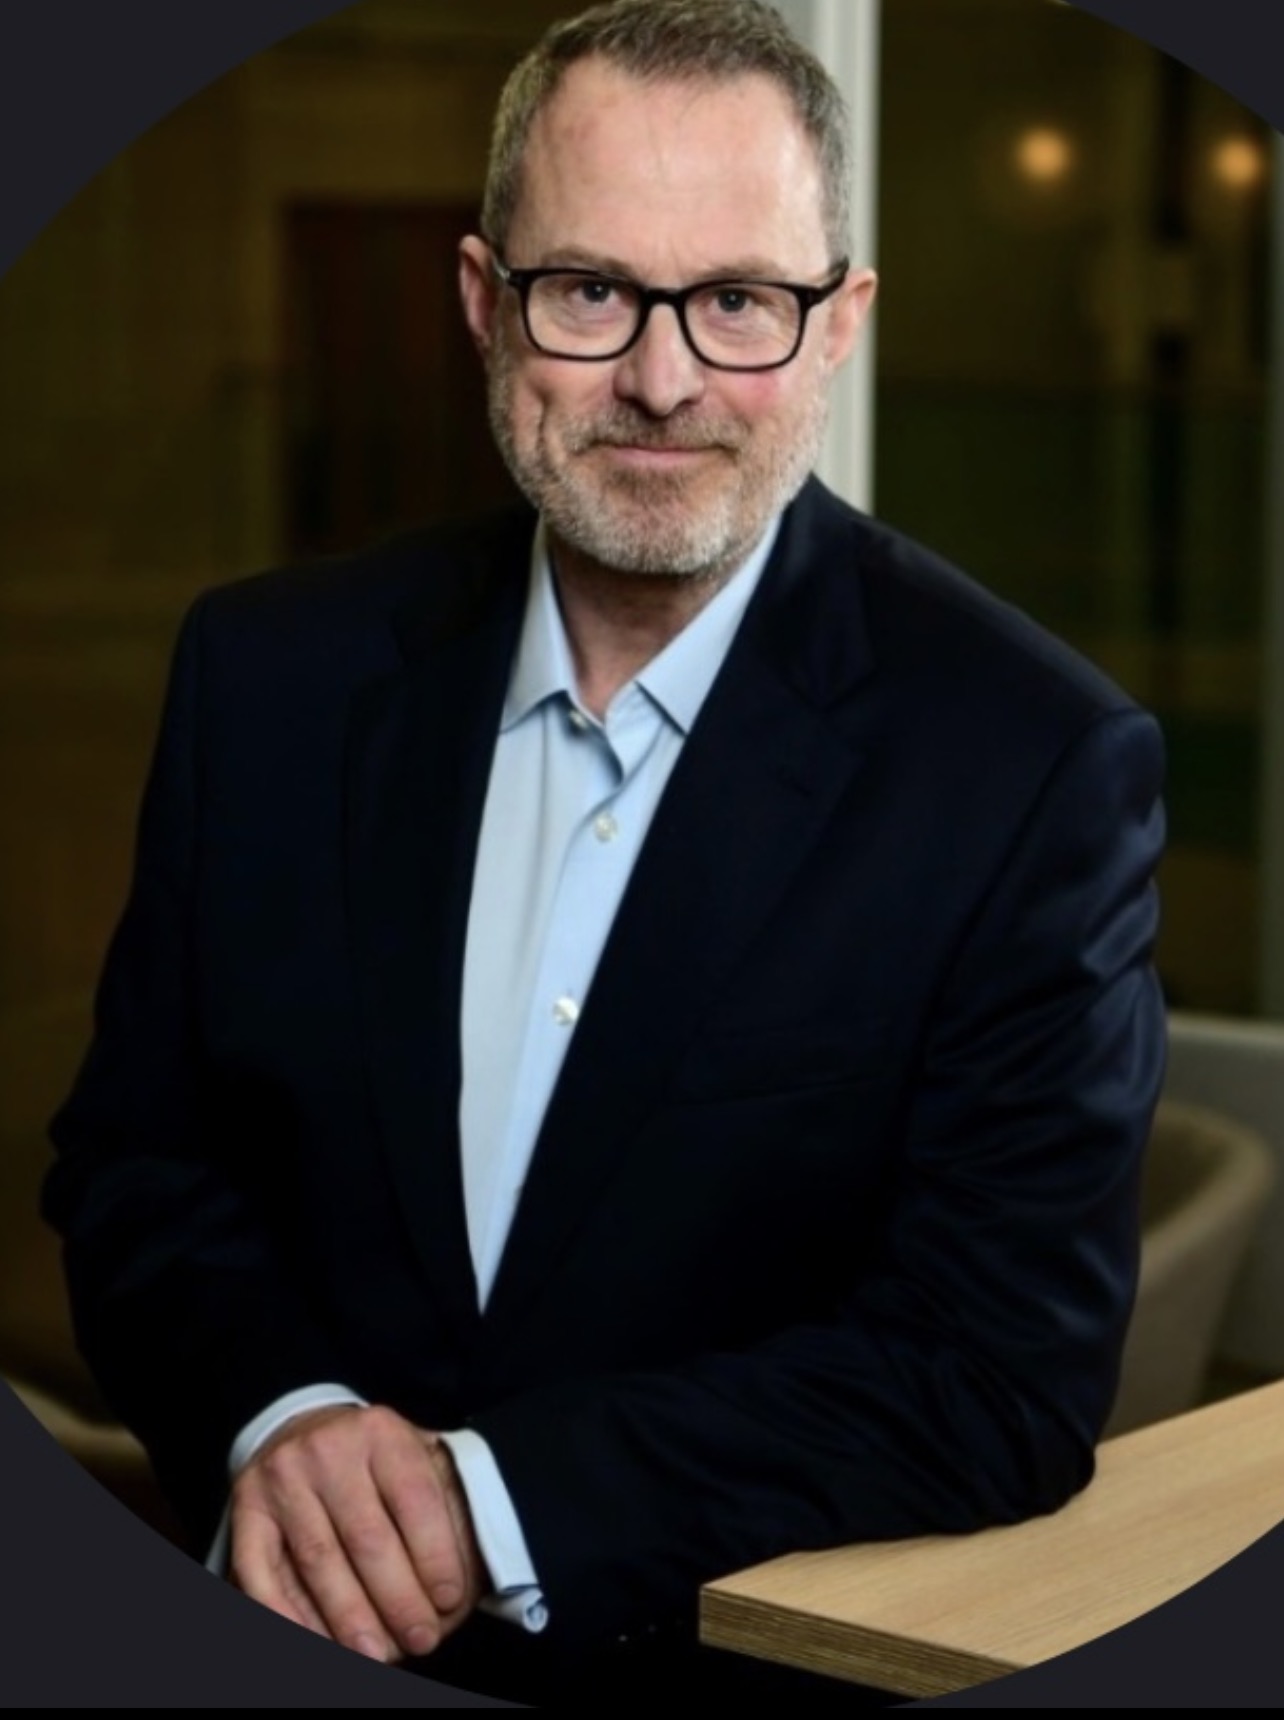
    Adam Wardi

    Adam Wardi

    Founder and Managing Partner

    Leads every Exit Advisory mandate from the first assessment to closing. Finance professional and entrepreneur with institutional capital markets expertise; has executed over $100 million of M&A and corporate development transactions across the United States and Scandinavia. Founded Saintrose to give owners of mid-sized private companies the standard of preparation and execution that larger companies take for granted.

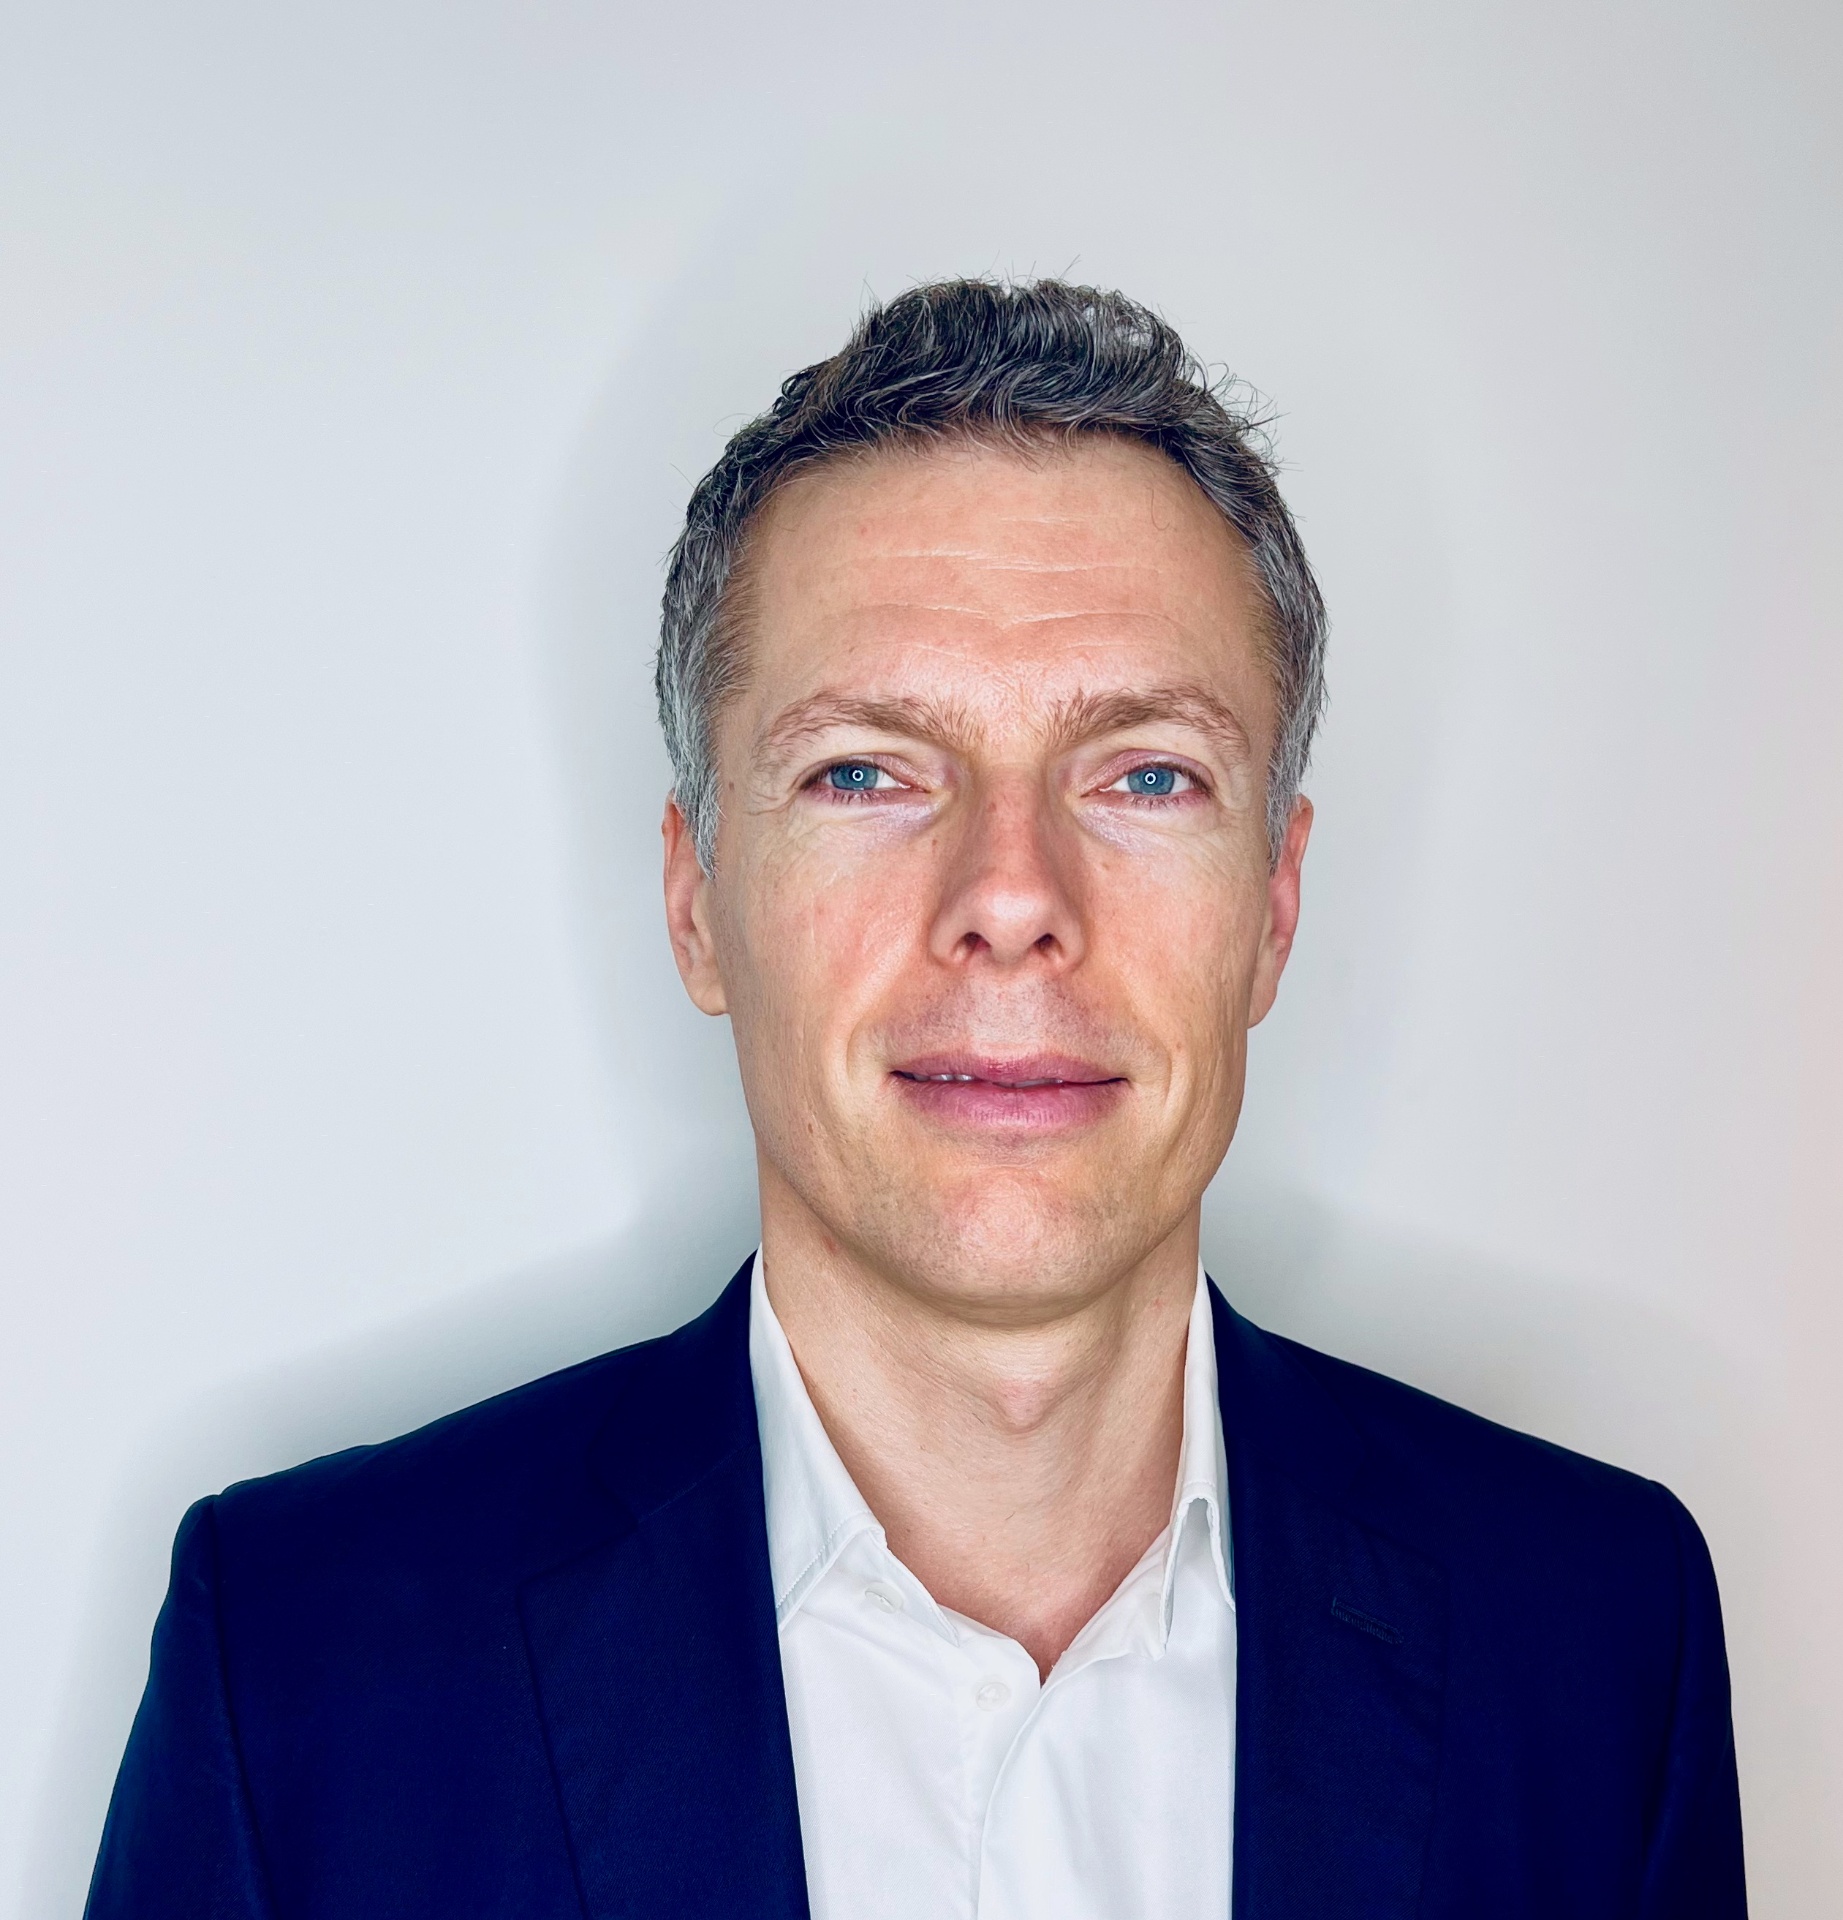
    Gary Ward

    Gary Ward

    Advisor

    Thirty years originating and closing complex transactions, including as Partner of a £1 billion mid-market private equity house. Career spans PwC through to private equity board roles. Gary has spent decades deciding what private companies are worth and what makes a buyer pay more for one. He brings that lens to every valuation and to the buyer universe for every sale.

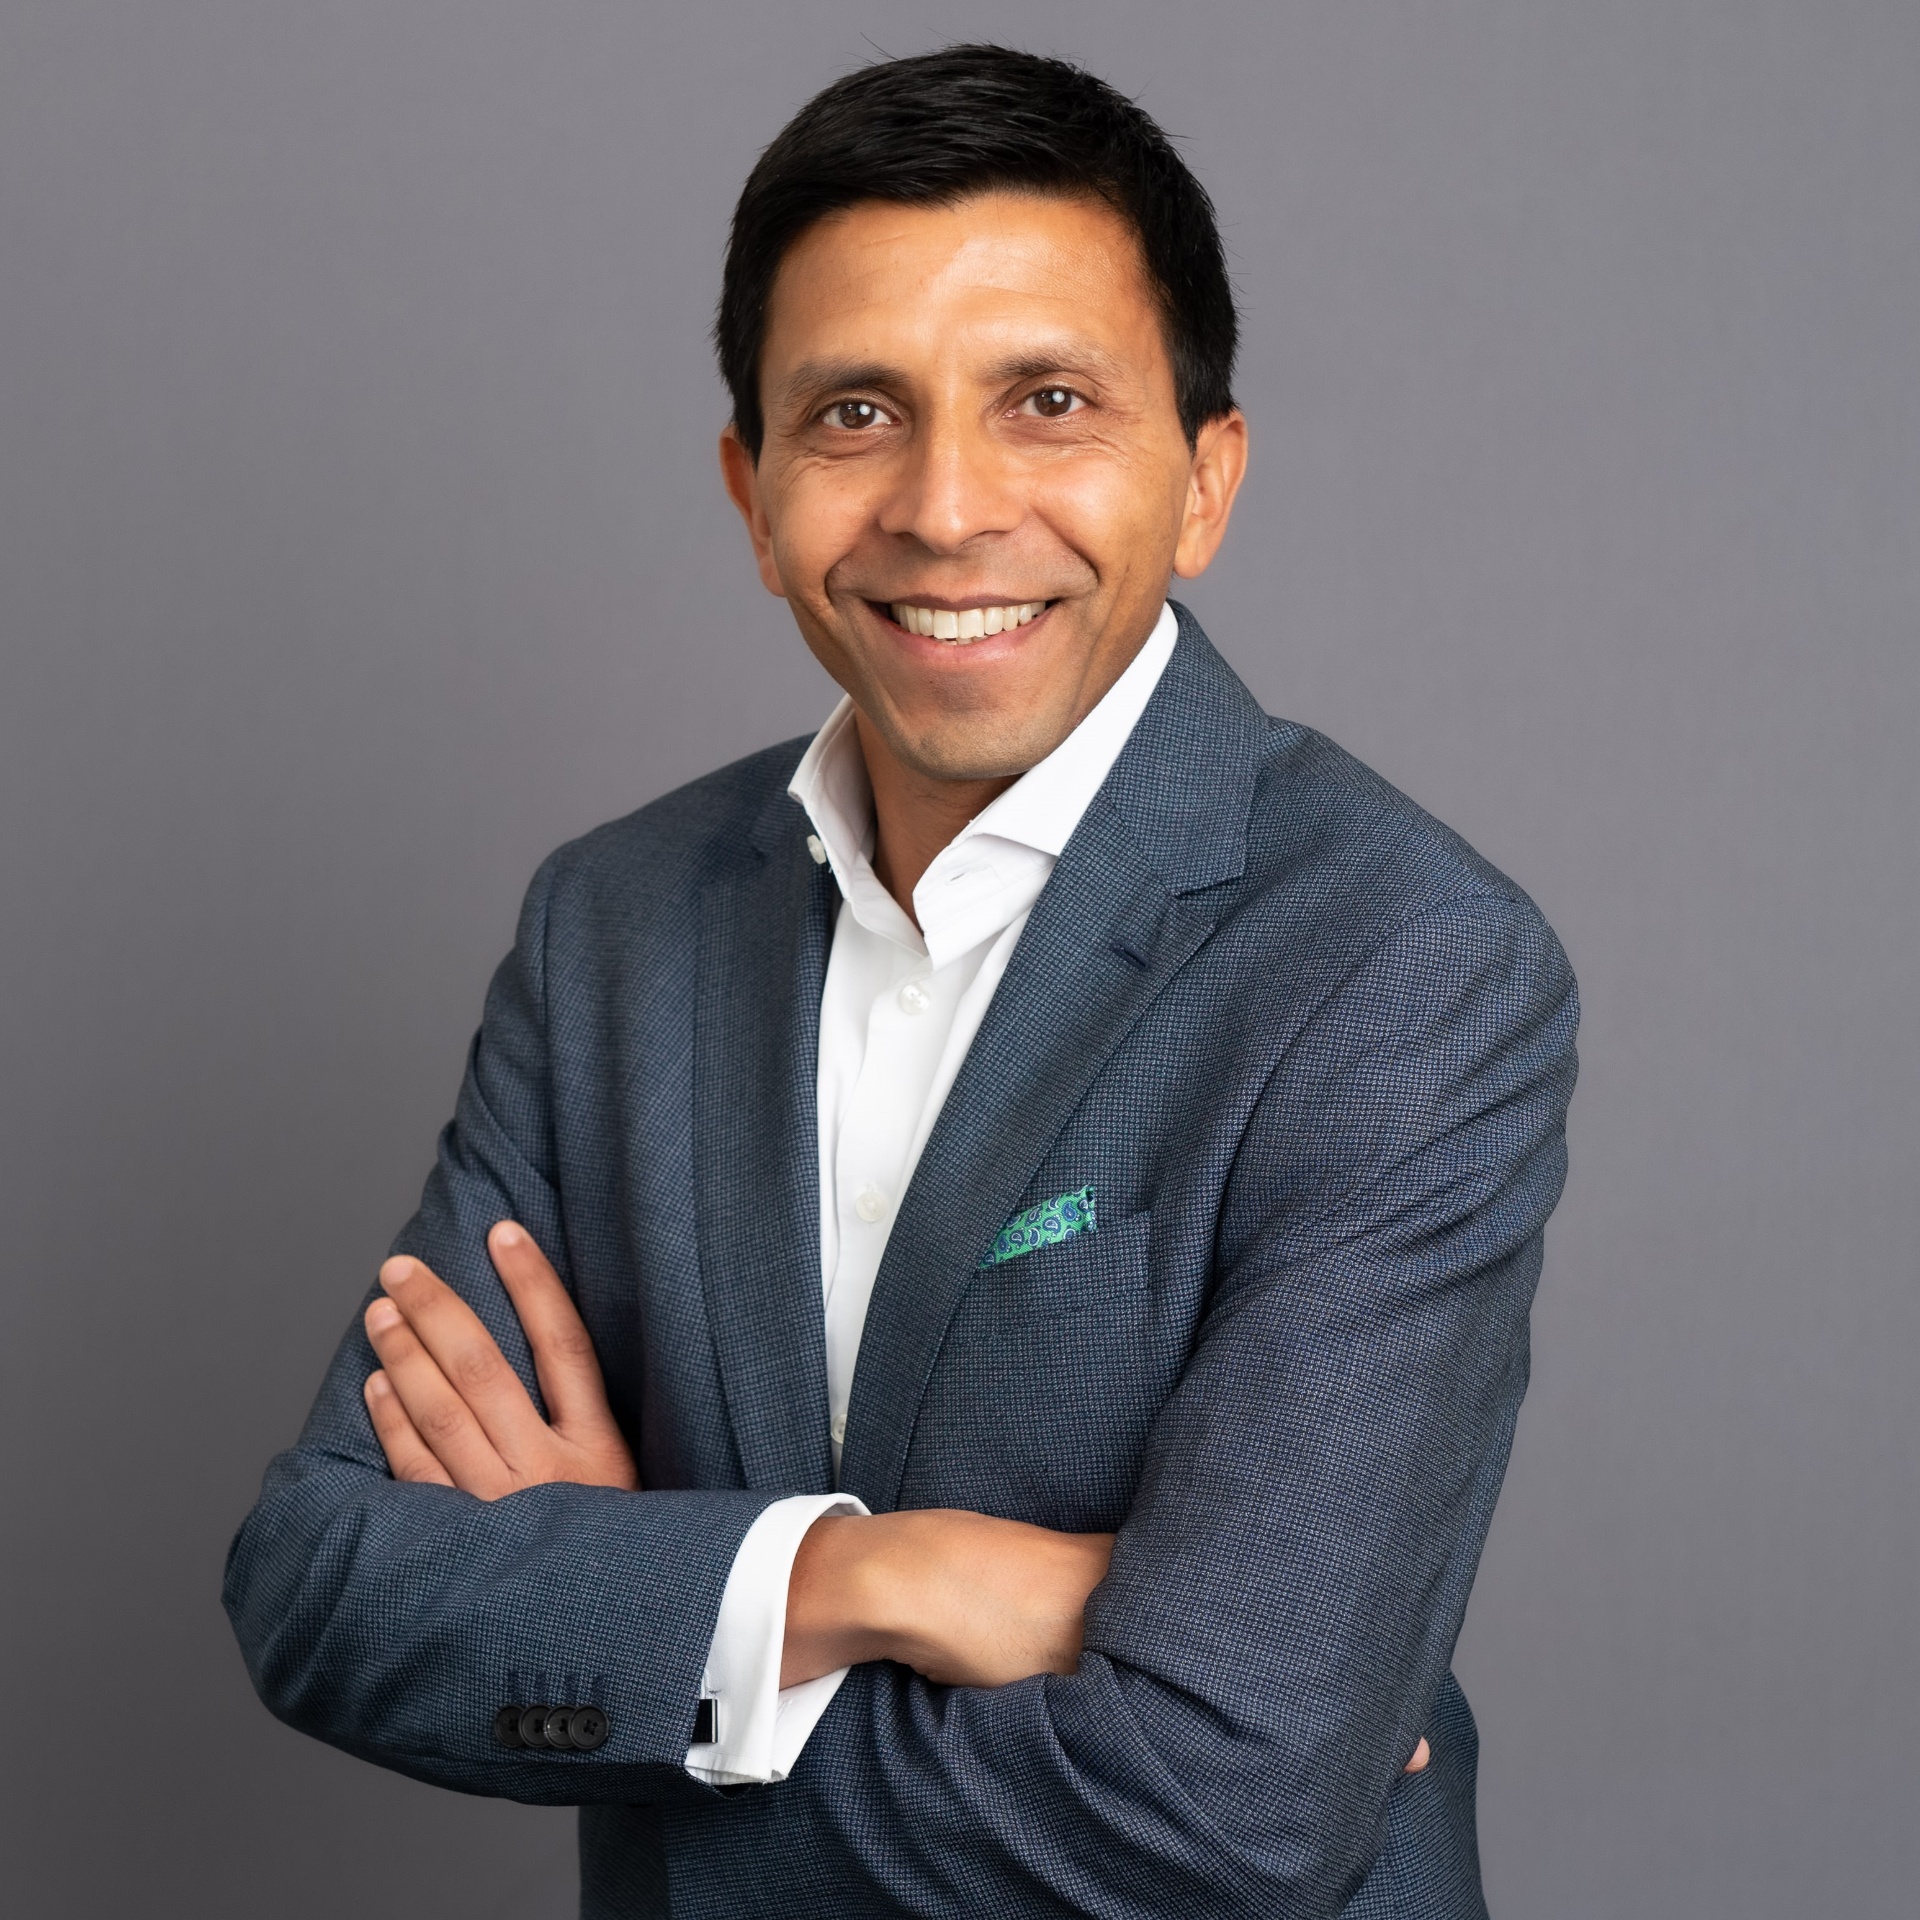
    Anil Mangla

    Anil Mangla

    Advisor

    More than twenty years in global financial services across BlackRock, where he was COO of a $400 billion institutional investor business, Barclays Capital, Sera Global (a Brookfield portfolio company) and Copenhagen Infrastructure Partners. Over his career Anil has advised on and enabled multi-billion fundraising strategies in private markets, and he brings the perspective of the institutional buyers and capital providers who increasingly sit across the table in mid-market transactions.

    Wayne Hiley

    Wayne Hiley

    Advisor

    Twenty years in corporate debt markets. Led Debt Structuring at Barclays UK Corporate Bank from 2010 to 2020 and raised over £200 billion as Head of Corporate Bond Syndicate. Most acquisitions are financed; Wayne reads your company the way a buyer's lender will, which is often what decides whether a buyer can pay the price.

    Behind the partners sits a deal team of associates and analysts across Zurich, Dubai and London who build the financial package, the evidence file and the buyer universe for every mandate.

    OUR ECONOMICS

    The same fee as a bank hired at launch. Part of it at risk.

    You are bringing your investment bank in early, not buying consulting and hiring a bank later. We charge the same transaction success fee whether we are engaged at launch or eighteen months before it. The engagement begins with an upfront engagement fee that is credited in full against the success fee when your company sells through us. The success fee itself is a percentage of transaction value that steps down as the transaction gets larger, and it is set out in full in the proposal.

    Once we have valued the company we agree, in writing, a Guaranteed Offer Threshold: the minimum enterprise value (the price for the whole business, before debt and cash) we are prepared to put part of our own economics behind once the agreed preparation plan is complete. It is set at the defensible lower bound of the post-preparation valuation range, not at the most optimistic case.

    If we bring you an offer at or above the threshold

    The guarantee is satisfied, whether or not you choose to accept that offer. The normal success fee applies if you sell.

    If the best offer is below the threshold and you sell anyway

    A discounted success fee applies. The upfront engagement fee is credited in full against that fee, and the success fee is reduced by the amount agreed in advance and fixed in the proposal.

    If we complete the agreed process and cannot produce an offer at all

    The upfront engagement fee is refunded.

    The conditions on your side are short and objective, and they sit in the engagement letter rather than in anyone's judgment after the fact: materially complete and accurate information; completion of the small number of preparation actions we agree in writing; no defined material deterioration from the agreed financial baseline unless the threshold is formally recalibrated; and permission for us to run the agreed competitive process for the agreed period.

    This is our economics behind our own valuation thesis. It is not a guarantee of a final sale price, of a specific buyer, or of your decision to accept an offer. What counts as an offer, and the conditions on both sides, are set out in the engagement letter. All valuation figures provided during an engagement are estimates based on company information, market evidence and professional judgment.
    FIT

    This works for a specific kind of owner.

    It is for you if:

    • Your company generates roughly $500,000 or more of EBITDA.
    • You are seriously considering a sale now or within the next two years.
    • The business is fundamentally sound and profitable. This is not a turnaround.
    • You are willing to make specific changes where the assessment shows they will improve the sale outcome.
    • Where preparation is needed, there is enough time and value at stake for it to matter economically.

    What Saintrose is not:

    Generic business coaching. A marketing agency. A fractional COO. Outsourced sales management. An executive search firm. A bookkeeping clean-up service. Management consulting. A broker who lists the company as it is and waits for the phone to ring.

    Saintrose is finance-led pre-exit value creation and transaction execution, run by the people who will sell the company.

    ILLUSTRATIVE COMPOSITE

    What closing the Value Gap can change.

    Consider a mechanical services contractor whose owner generates most new business and whose sales process is weak and undocumented. Two preparation priorities are agreed: install a sales process that produces a forecastable pipeline, and put a sales leader other than the founder in front of customers. Over fourteen months, the company implements and proves both changes, and the updated valuation supports the prepared range below.

    Illustrative comparison before and after preparation
    As the company wasWhat it could support
    Normalized EBITDA$2.5 million$3.0 million
    Multiple a buyer would apply4.5x to 5.0x6.0x to 6.5x
    Enterprise value$11.3 million to $12.5 million$18.0 million to $19.5 million
    Cash paid at closing$7.9 million to $10.0 million (70 to 80 percent). The rest is an earnout, paid only if the earnings hold for two to three years after the sale$18.0 million to $19.5 million. Essentially the full price, paid at closing
    WhyThe sales depend on the founder, so the buyer holds back part of the price to keep him in the chair until the earnings prove outA sales leader and a sales process the buyer can see working without the founder. There is nothing left for the buyer to protect, and nothing to keep him for
    Owner's time commitment after the saleTwo to three years, because the earnout is only paid if he stays and the earnings holdA handover of a few months. With the full price paid at closing, nothing ties him to the business

    The Guaranteed Offer Threshold is set at $18.0 million, the defensible lower bound of the prepared range. After fourteen months and completion of the two preparation priorities, the company is marketed with evidence buyers can verify.

    Illustrative composite, not a client transaction. These figures are hypothetical valuation assumptions, not evidence of a realized result or a promise of a sale price. Valuation, timing, terms and outcomes vary by company and market.

    QUESTIONS

    Why not just go to market now and see what I get?

    If the assessment shows your company is ready, that is exactly what we recommend. We move straight to marketing and closing, with several serious buyers competing on price and terms. If a few specific fixes are likely to improve the outcome enough to justify the time, we recommend those first. Preparation is not a compulsory waiting period.

    I do not have the time. I am running the company.

    That is the problem we are fixing. The first things we take off your desk are the ones that make the company dependent on you, which is also why a buyer cannot buy it without keeping you.

    I am not certain I want to sell in two years.

    Then you are a good client. Everything in the first two pillars makes the company more predictable, more transferable and better managed whether you sell or not. If you decide not to, you own a better company. If you decide to, you are eighteen months ahead of every owner who decided first.

    How long does preparation take?

    It is skipped when the company is ready. Where preparation pays, we revisit the number every 60 to 90 days and stop the moment another cycle is not expected to add more value than it costs in time. The sale process then moves into marketing and closing.

    Who actually does the work?

    We value the company, pick the constraint, provide the playbooks and templates, review implementation, analyze performance and run the transaction. Your team makes the operating decisions, implements the systems, hires and manages people, runs the meetings and produces the evidence that the changes work.

    Find out what your company is worth to a buyer.

    The first conversation is thirty minutes with a partner. We will tell you what a buyer is likely to see, whether preparation would change it, and whether Saintrose is the right firm to run your sale. If your company is already ready, we will tell you that too.